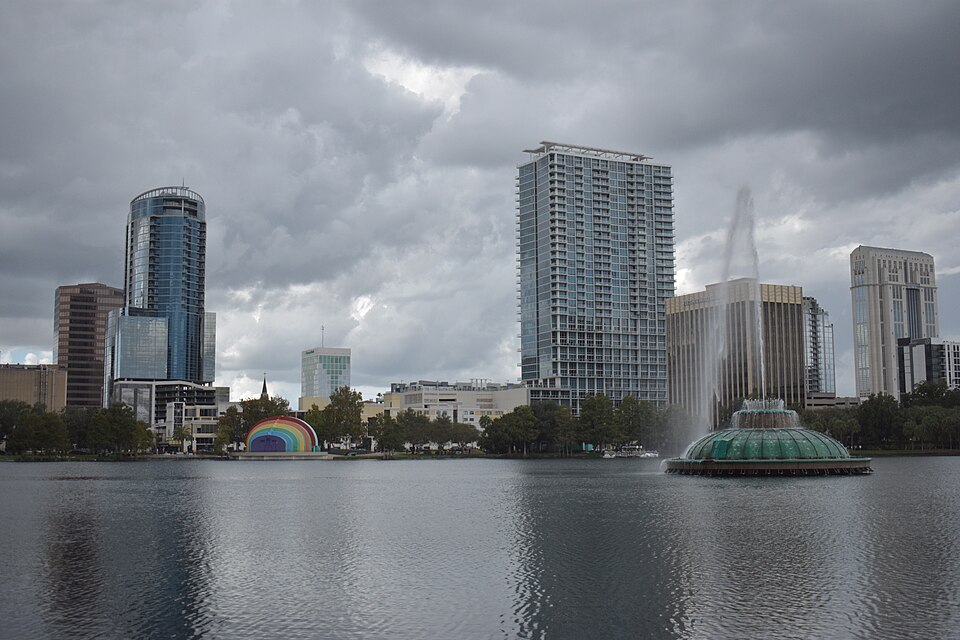exa — ten to the eighteenth powerI-4 CORRIDOR
REAL ESTATE SERVICES LLC
Real Estate & Tax Education
In Collaboration WithTHE TAX CUTTERY®

For The Real Estate Professional · Real Estate + Federal Tax

Build A Financial Plan Behind Every Closing.

You work for the commission. Put the business around it to work too.

The Guide is optional for return preparation and required for Tax Advisory. The free initial consultation is online and self-guided.

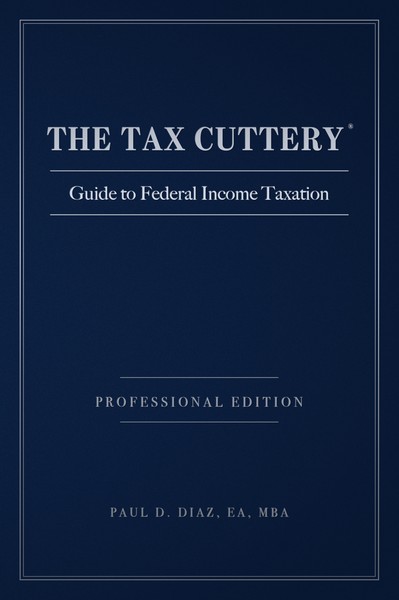
Actual front cover of THE TAX CUTTERY® Guide to Federal Income Taxation, Professional Edition

The Book Behind The Practice

THE TAX CUTTERY® Guide to Federal Income Taxation, Professional Edition

This is the cover of the hardcover casebound 564-page Guide.

Lake Eola fountain in front of the real downtown Orlando skyline
Orlando · Lake EolaPhoto: JER3L1337 · Source · CC BY 4.0 · Display Crop
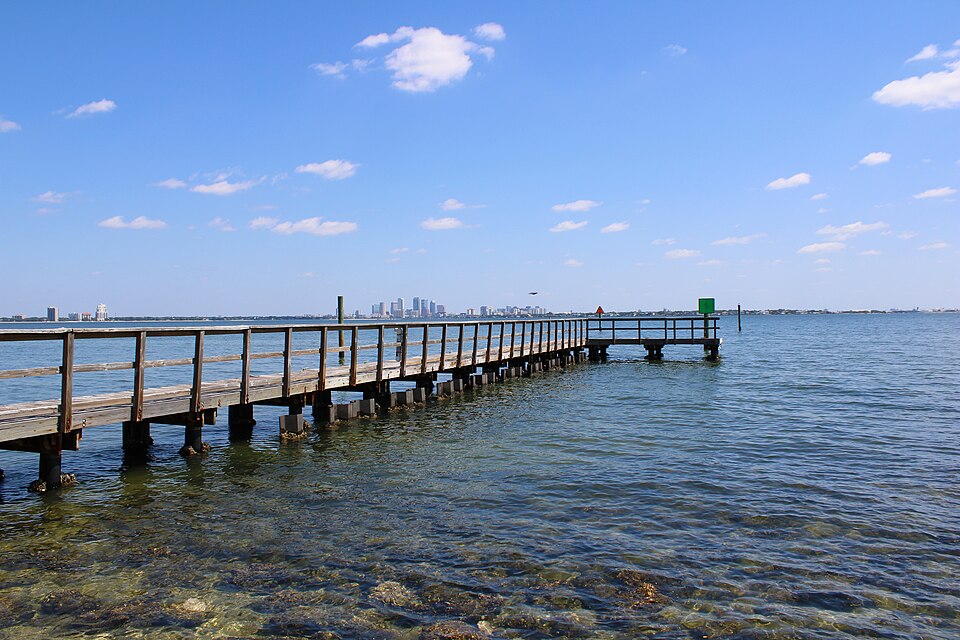
Tampa skyline across the water from Ballast Point Park
Tampa · Ballast PointPhoto: Trevorrrrvalent · Source · CC BY 4.0 · Display Crop

Tax Planning For Real Estate Agents & Brokers

Your Next Closing Should Fit A Bigger Plan

A commission is the beginning of the business calculation. Operating costs, payment timing, entity decisions and the household’s financial needs all compete for the same dollars. Planning means seeing those decisions together before a strong quarter becomes a difficult tax payment.

A licensee’s own business tax questions are also different from the questions raised by a client’s property. Learn to recognize both without assuming that a real-estate license settles a federal tax issue. The Guide provides a reference you can return to as your practice and responsibilities grow.

44 · Build The Business Behind The Commission.

What Tax Questions Should A Real Estate Licensee Plan For?

Commission income, business expenses, tax classification and payment timing belong in the same business plan. A strong closing month can create a cash-flow problem if tax is an afterthought. The Guide connects income, deductions and the professional’s wider household picture.

In The Guide: §2.4.1 · §3.6 · §6.1 · §9.1
Explore The Full Framework In The Guide ↗
IRS Sources & Related Guidance

IRS · Self-Employed Tax Center ↗

45 · A Business Expense Needs A Business Story.

Can I Deduct Marketing, Software And Other Practice Costs?

Ordinary and necessary business costs may be deductible when the requirements are met. Keep the amount, purpose and supporting documents. Personal spending and capital costs need separate analysis. The Guide’s deduction and substantiation chapters help turn a stack of charges into a defensible business record.

In The Guide: §3.6 · §3.10 · §6.6 · §20.3
Explore The Full Framework In The Guide ↗
IRS Sources & Related Guidance

IRS · Recordkeeping ↗

46 · Track The Business Use. Keep The Evidence.

How Should A Licensee Approach Vehicle And Home-Office Deductions?

These deductions have their own eligibility and substantiation rules. Commuting, personal use, business travel and a qualifying workspace are different facts. The Guide explains why documentation matters. Keep contemporaneous records and review the particular deduction instead of treating every mile or spare room as business use.

In The Guide: §3.6 · §3.10 · §6.6 · §20.1
Explore The Full Framework In The Guide ↗
IRS Sources & Related Guidance

IRS Publication 463 · Travel, Gift And Car Expenses ↗
IRS Publication 587 · Business Use Of Your Home ↗

47 · Pay Yourself With The Structure In View.

Do Payroll And Expense Reimbursements Matter In A Brokerage Business?

Compensation and reimbursements depend on the entity and the working arrangement. The Guide compares wages, pass-through income and accountable plans. Match the paperwork to the actual ownership and services before using a payroll or reimbursement approach copied from another business.

In The Guide: §9.3 · §10.3 · §10.14
Explore The Full Framework In The Guide ↗
IRS Sources & Related Guidance

IRS · Self-Employed Tax Center ↗

48 · Turn A Strong Business Into A Longer Plan.

Can A Self-Employed Real Estate Professional Plan For Retirement?

Yes. The available arrangement depends on the business, eligible workers, earnings and the rules of the chosen plan. The Guide connects compensation and retirement planning. The right tax conversation starts with the whole practice and family, not a contribution limit quoted without context.

In The Guide: §10.1 · Chapter 11
Explore The Full Framework In The Guide ↗
IRS Sources & Related Guidance

IRS Publication 560 · Retirement Plans For Small Business ↗

Your Next Closing Should Fit A Bigger Plan

Start the consultation with how the practice is organized and what changed in income, expenses, staffing or family circumstances. Tax return preparation, Tax Advisory and any other professional deliverable are separately scoped.

The book gives you the framework to ask a better question. The consultation gives the firm the context to understand your concern. Professional work begins with an agreed scope; a book purchase does not include tax preparation, representation or a private analysis.

$299 hardcover. Shipping and applicable taxes are shown at checkout. Already own it? Register Your Copy →

Follow The Source.

These are starting points for education. Check the revision, applicable tax year and current law before relying on a rule for a transaction.

The Guide’s references point to the relevant discussion; they do not establish your eligibility for a deduction, exclusion or tax treatment.
Keep The Ownership Cycle In View

Explore All 53 Tax Topics →

Save Smarter. Prepare Accurately. Defend Better.

The Property Is Part Of
Your Whole Tax Life.

I-4 Corridor Real Estate Services LLC + THE TAX CUTTERY LLC
Joint education. Distinct companies. Separately scoped professional services.