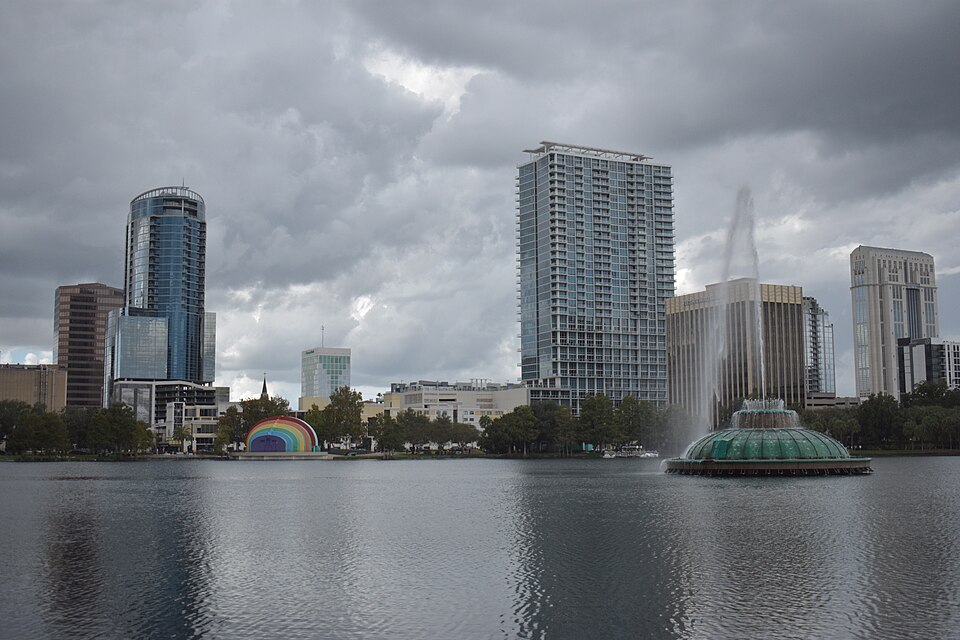exa — ten to the eighteenth powerI-4 CORRIDOR
REAL ESTATE SERVICES LLC
Real Estate & Tax Education
In Collaboration WithTHE TAX CUTTERY®

When The IRS Enters The Picture · Real Estate + Federal Tax

Own The Property. Keep The Evidence.

A well-organized file gives the tax story something solid to stand on.

The Guide is optional for return preparation and required for Tax Advisory. The free initial consultation is online and self-guided.

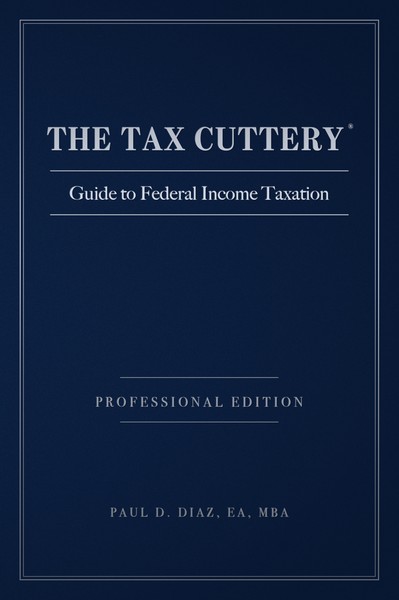
Actual front cover of THE TAX CUTTERY® Guide to Federal Income Taxation, Professional Edition

The Book Behind The Practice

THE TAX CUTTERY® Guide to Federal Income Taxation, Professional Edition

This is the cover of the hardcover casebound 564-page Guide.

Lake Eola fountain in front of the real downtown Orlando skyline
Orlando · Lake EolaPhoto: JER3L1337 · Source · CC BY 4.0 · Display Crop
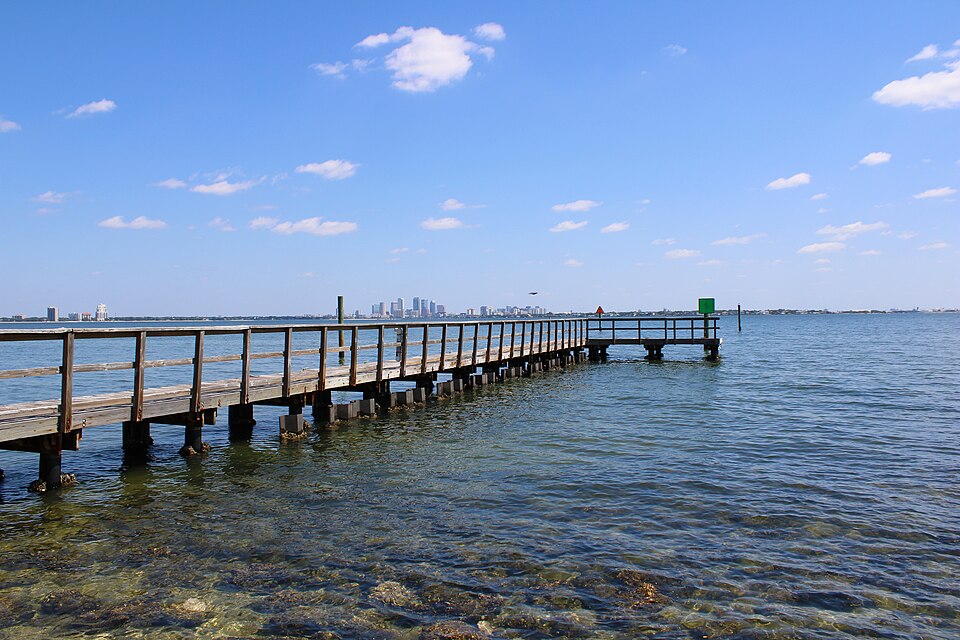
Tampa skyline across the water from Ballast Point Park
Tampa · Ballast PointPhoto: Trevorrrrvalent · Source · CC BY 4.0 · Display Crop

Real Estate IRS Notices, Liens & Tax Records

Bring The Notice And The Facts Into The Same File

When the IRS asks about a property transaction, the response begins with what was actually reported and the records behind it. A closing statement, an invoice, a depreciation schedule and a participation record establish different facts. A pile of documents is useful only when the history can be followed.

A notice, a lien issue, foreclosure or casualty can add deadlines and separate work to that history. Read the actual document and preserve the dates. The questions here explain the starting points; the consultation helps the firm understand which issue and tax year need attention.

49 · Keep A File That Can Tell The Whole Story.

Which Records Should Follow A Property From Purchase To Sale?

Contracts, closing statements, basis allocations, improvement invoices, depreciation schedules, leases and prior filings connect the ownership history. The Guide’s substantiation framework explains why the file matters. Organize it while the facts are available, rather than reconstructing years of decisions after an IRS question arrives.

In The Guide: §6.6 · §12.10.1 · §12.10.2 · §12.10.3 · §18.5 · §20.3
Explore The Full Framework In The Guide ↗
IRS Sources & Related Guidance

IRS · Recordkeeping ↗

50 · A Notice Deserves A Records Check.

What If The IRS Questions My Real Estate Reporting?

Read the notice, identify the year and issue, and follow the stated response date. The Guide explains examination and penalty procedures as well as the underlying tax rules. A factual, supported response starts with the actual filed return and the records behind the property transaction.

Explore The Full Framework In The Guide ↗
IRS Sources & Related Guidance

IRS · Audits ↗

51 · A Lien Can Reach The Closing Table.

How Can A Federal Tax Lien Affect A Property Transaction?

A federal tax lien and a levy are different enforcement tools. A proposed sale or refinance may require specific lien-related work. The Guide explains the collection framework. Tell the firm about the planned closing early; obtaining the right relief requires its own facts and process.

In The Guide: §21.5 · §21.5.1 · §21.5.3 · §21.9
Explore The Full Framework In The Guide ↗
IRS Sources & Related Guidance

IRS · Understanding A Federal Tax Lien ↗

52 · Losing The Property May Not End The Tax Questions.

Can Canceled Property Debt Create Taxable Income?

Canceled debt and the disposition of property can create separate tax questions. Debt terms, exclusions and basis adjustments may matter. The Guide introduces discharge-of-indebtedness income and collection concerns; the current IRS foreclosure and canceled-debt guidance is essential for the particular transaction.

In The Guide: §2.4 · §21.5
Explore The Full Framework In The Guide ↗
IRS Sources & Related Guidance

IRS Publication 4681 · Canceled Debts And Foreclosures ↗

53 · When The Exit Was Not Your Choice.

Can Destruction Or Condemnation Raise A Tax-Deferral Question?

A casualty, taking or similar event can create gain as well as loss questions. Section 1033 may permit deferral when its requirements are met. The Guide places involuntary conversions in the recognition framework. Preserve insurance, award and replacement records before deciding how to report the event.

In The Guide: Chapter 5
Explore The Full Framework In The Guide ↗
IRS Sources & Related Guidance

IRS Publication 544 · Dispositions Of Assets ↗

Bring The Notice And The Facts Into The Same File

Describe the actual notice or transaction in the consultation and identify any deadline. Do not post private documents publicly. Secure intake and a defined engagement come before individualized professional work.

The book gives you the framework to ask a better question. The consultation gives the firm the context to understand your concern. Professional work begins with an agreed scope; a book purchase does not include tax preparation, representation or a private analysis.

$299 hardcover. Shipping and applicable taxes are shown at checkout. Already own it? Register Your Copy →

Follow The Source.

These are starting points for education. Check the revision, applicable tax year and current law before relying on a rule for a transaction.

The Guide’s references point to the relevant discussion; they do not establish your eligibility for a deduction, exclusion or tax treatment.
Keep The Ownership Cycle In View

Explore All 53 Tax Topics →

Save Smarter. Prepare Accurately. Defend Better.

The Property Is Part Of
Your Whole Tax Life.

I-4 Corridor Real Estate Services LLC + THE TAX CUTTERY LLC
Joint education. Distinct companies. Separately scoped professional services.