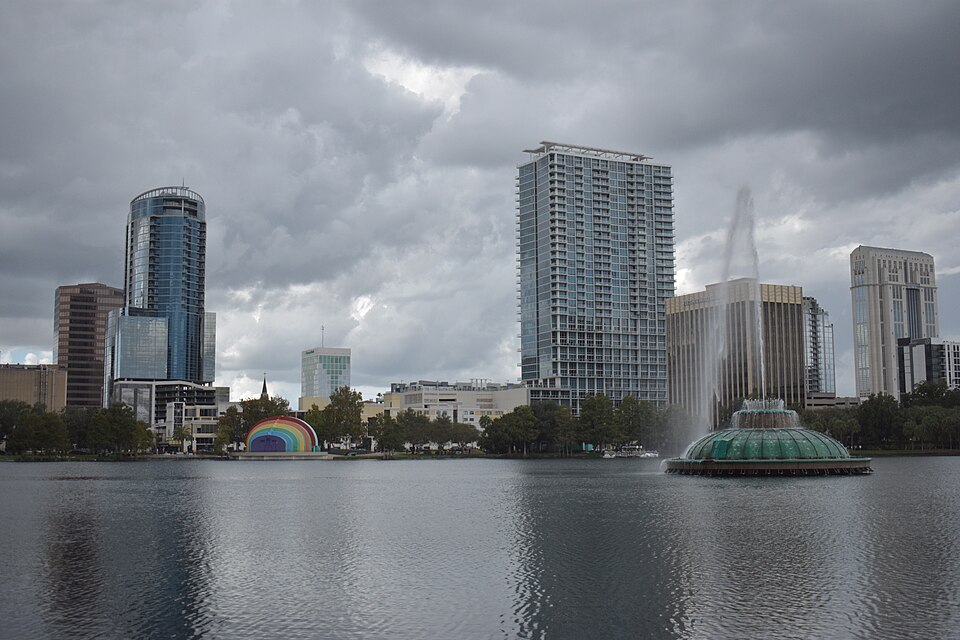exa — ten to the eighteenth powerI-4 CORRIDOR
REAL ESTATE SERVICES LLC
Real Estate & Tax Education
In Collaboration WithTHE TAX CUTTERY®

Beyond Your Holding Period · Real Estate + Federal Tax

A Property Can Outlive Its Owner. Its Records Should Too.

The next generation needs more than the keys.

The Guide is optional for return preparation and required for Tax Advisory. The free initial consultation is online and self-guided.

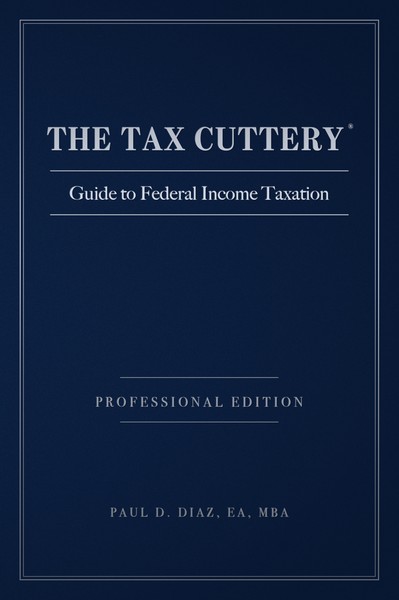
Actual front cover of THE TAX CUTTERY® Guide to Federal Income Taxation, Professional Edition

The Book Behind The Practice

THE TAX CUTTERY® Guide to Federal Income Taxation, Professional Edition

This is the cover of the hardcover casebound 564-page Guide.

Lake Eola fountain in front of the real downtown Orlando skyline
Orlando · Lake EolaPhoto: JER3L1337 · Source · CC BY 4.0 · Display Crop
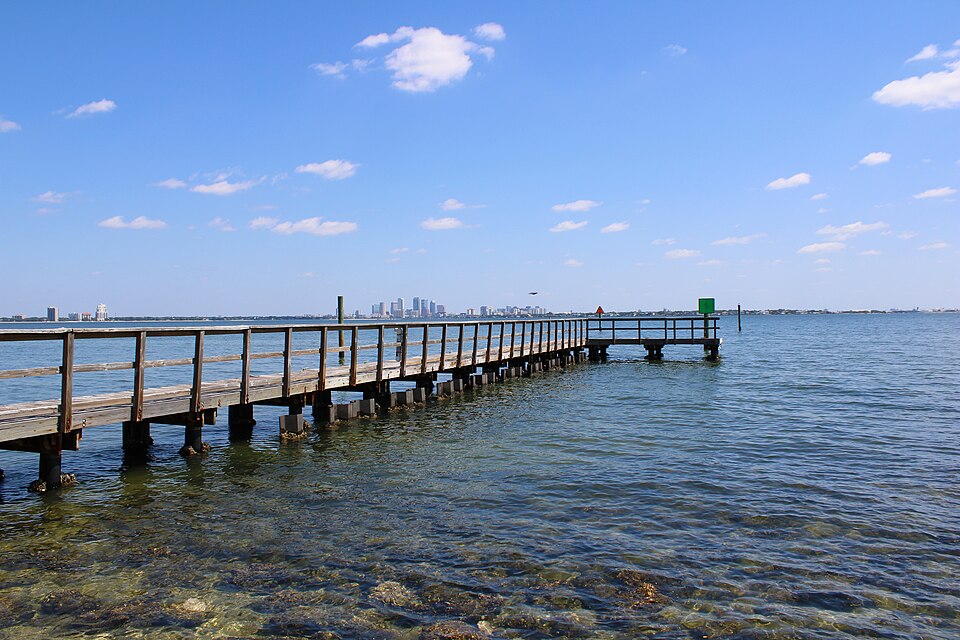
Tampa skyline across the water from Ballast Point Park
Tampa · Ballast PointPhoto: Trevorrrrvalent · Source · CC BY 4.0 · Display Crop

Inherited & Gifted Real Estate: Basis, Estates & Giving

Keep The History With The Property

A lifetime gift and an inheritance can transfer the same building with different tax histories. The ownership facts, timing, valuation and applicable rules matter. A family decision deserves a coordinated look at the legal transfer and the income-tax consequences.

Real estate can also connect an estate, a trust, continuing rental income and a charitable goal. These are not interchangeable filings or services. Start with who owns the asset, who receives the benefit and what happens next; then identify the records and professional work needed for that plan.

40 · A Gift Transfers A Tax History Too.

What Should I Consider Before Giving Property To Family?

A deed transfer can create reporting, valuation and future income-tax consequences. Gifted property often carries the donor’s basis history, subject to special rules. The Guide connects generosity with family planning. Coordinate the tax work, legal documents and valuation before the transfer is final.

In The Guide: §2.5.2 · §14.2 · §14.2.2 · §14.2.3
Explore The Full Framework In The Guide ↗
IRS Sources & Related Guidance

IRS · Gift Tax ↗
IRS Publication 551 · Basis Of Assets ↗

41 · Think Beyond The Next Closing.

What Happens To Basis When Real Estate Is Inherited?

Qualifying property acquired from a decedent generally receives a basis adjustment under Section 1014. The adjustment can be upward or downward; exceptions and ownership facts matter. The Guide connects that rule with lifetime holding and exchange decisions. Preserve valuations and estate records for the next owner.

In The Guide: §12.5.5 · §12.10.4 · §15.2 · §15.2.1
Explore The Full Framework In The Guide ↗
IRS Sources & Related Guidance

IRS Publication 551 · Basis Of Assets ↗

42 · The Estate And Its Income Are Different Questions.

How Do Estate And Trust Returns Connect To Real Estate?

Property at death can raise transfer-tax, basis and continuing income-reporting questions. Those are related but distinct obligations. The Guide puts estate planning into the income-tax picture. Identify the owner, fiduciary, beneficiaries and intended disposition before deciding which filings and professional engagements are needed.

In The Guide: §12.10.4 · §15.3 · §15.6
Explore The Full Framework In The Guide ↗
IRS Sources & Related Guidance

IRS · Estate Tax ↗

43 · Build A Legacy With The Full Cost In View.

Can Donating Appreciated Real Estate Fit A Tax Plan?

A charitable transfer can connect a philanthropic goal with tax planning. Qualification, valuation, deduction limits and transaction structure need review; not every gift produces the same benefit. The Guide examines appreciated property and charitable vehicles. Start with the intended impact, then evaluate the actual asset and recipient.

In The Guide: §15.4 · §15.4.1 · §15.4.2 · §15.4.4 · §15.4.5 · §15.6.2 · §15.6.3
Explore The Full Framework In The Guide ↗
IRS Sources & Related Guidance

IRS Publication 526 · Charitable Contributions ↗

Keep The History With The Property

Tell the consultation whether you are planning a transfer or handling one that already happened. Include the relationship, ownership, timing and intended outcome; supporting documents belong in the secure intake.

The book gives you the framework to ask a better question. The consultation gives the firm the context to understand your concern. Professional work begins with an agreed scope; a book purchase does not include tax preparation, representation or a private analysis.

$299 hardcover. Shipping and applicable taxes are shown at checkout. Already own it? Register Your Copy →

Follow The Source.

These are starting points for education. Check the revision, applicable tax year and current law before relying on a rule for a transaction.

The Guide’s references point to the relevant discussion; they do not establish your eligibility for a deduction, exclusion or tax treatment.
Keep The Ownership Cycle In View

Explore All 53 Tax Topics →

Save Smarter. Prepare Accurately. Defend Better.

The Property Is Part Of
Your Whole Tax Life.

I-4 Corridor Real Estate Services LLC + THE TAX CUTTERY LLC
Joint education. Distinct companies. Separately scoped professional services.